Friday, 5 August 2016

Where is the Rupee headed?

"People know the price of everything, but the value of nothing" - Oscar Wilde

Since 2008 we have seen sharp correction in rupee against major currencies of the world. The INR has moved from 39 to 67 levels against dollar in 8 years which numerically speaking is a 71% correction in 8 years or an almost 7% annualized correction. Majority of us believe that we still have an inflation differential of close to 4% with developed countries and that will be reflected in currency depreciation. Consensus on the street suggests that INR will continue to lose 3-4% every year to remain competitive.

In my opinion it’s extremely important to crystal gaze the relative value of rupee against major currencies. Economics suggests that prices are determined by supply and demand. RBI has kept supply of rupee in check for the last four to five years due to which we witnessed deficit liquidity in that period. This was primarily done to control inflation.

Contrary to India, majority of developed countries were following easy monetary policy. They tried to keep real interest rate negative to push up asset prices, especially real estate.

·         Rupee Supply – RBI today has structurally brought down inflation by keeping rupee supply in check. There was limited monetary expansion due to this tightening of liquidity. Going forward liquidity will ease and RBI will ensure steady expansion in money supply which will increase supply of rupee in the system.

·         Rupee Demand – In the past few years we have opened up our economy and allowed FDI in few of the largest sectors of the economy like railway & defense. Passage of GST constitutional amendment bill will encourage more FDI & FII flow in the country. The stability shown by INR in the past three years is helping foreign investors gain confidence. Fall in commodity prices has significantly improved the balance of payment situation. Also in a world of monetary expansion, INR being short in supply will start gaining because of demand supply mismatch.

As Carl Richard quotes – “Tomorrow’s Market Probably Won’t Look Anything Like Today”. I would like to remind you all of a period between 2003 - 2008 where rupee gained against dollar over an five year period. Common sense tells us that we are going to witness something similar.
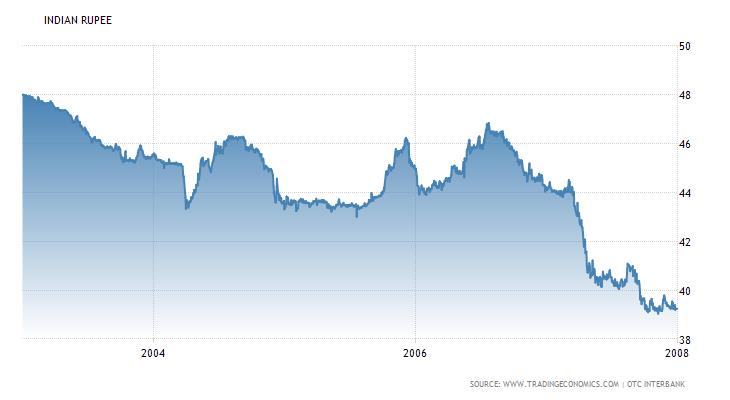
 

We would like to put our thoughts on asset class behavior during time to come –

·         Debt – Currency appreciation will create deflationary trend in the economy. In that environment rates will fall faster and deeper than what we anticipate. Majority of us are taking reinvestment risk in our portfolio by being on the shorter end of the curve. I would urge investors to lock their yield at a higher rate by investing in long term funds. Also I would urge people to buy quality and liquid papers where there is no credit risk.

·         Equity - Currency appreciation will help majority of domestic facing companies primarily due to lower input cost. GST and FDI in railway & defense will also help towards this cause.  I would urge investors to look at domestic facing companies from auto, auto ancillary, FMCG, engineering, cement, logistics and other allied manufacturing industry as they look poised to create a multiyear trend.

Tuesday, 1 March 2016

Budget - 2016

Changing Guard

Markets entered budget day on a bearish note anticipating negative outcome from Budget 2016. There were expectations of a 2% hike in service tax rate from 14.50% to 16.50%. It was also expected that LTCG on equities will be extended from one year to three years while some quarters were expecting the same to be taxed as well. What surprised the street was neutral stand on taxes and moderate increase in overall tax revenue. We did our own study of Budget 2016 and in our opinion it’s a CHANGE OF GUARD for the Indian economy.

1.       From services to agriculture & manufacturing – most of the thrust in the budget is towards agriculture, infrastructure and some manufacturing sectors. The budget is neutral to negative for services with marginal increase of 0.50% as agriculture cess. Agriculture, infrastructure & manufacturing are the biggest job providing sectors. Budget has given huge outlay for roads, irrigation, allied agriculture sectors and some of the manufacturing sectors got incentivized with change in excise and custom duty. This will help to balance the economy and increase weight of manufacturing sector in the economy.

2.       From urban to rural economy – this budget has focused on building rural economy by focusing on social welfare schemes and outlay for agriculture sector. Also outlay for roads will help in connecting villages. Higher taxes for four wheelers @ 1% to 4% is a clear signal that the government’s focus is to build rural India at the cost of urban India. This will help in reducing income inequality, improve rural wages and improve social infrastructure of country.

3.       From rich Individuals to poor people – some of the taxes like additional surcharge for Rs. one crore plus income and 10% dividend distribution tax for individual earning more than Rs. 10 lac dividend income is a clear sign that rich people will have to pay more taxes to benefit the poor.

4.       From profit & loss account to balance sheet – the government has been levying higher taxes on diesel and petrol over the last year. The budget has given direction that this amount will be spent on making roads. For last so many years we are struggling to convert our economy from consumer led to investment led. This budget will help in changing direction of economy towards investment.


In our opinion this budget was a balancing act and will try to move economy towards sustainability. This CHANGE OF GUARD will create wonderful opportunities for large sectors and companies. Sectors like two wheelers, cement, agri input, auto ancillary, chemicals, consumer durable, rural consumption and other allied sectors will gain. We strongly believe that this CHANGE OF GUARD will help some of the business to grow at higher pace and hence get premium valuations compared to the market. The recent correction has made this story more compelling.

Tuesday, 18 August 2015

Market Hunts for Breakout

Reference: “Are we in a structural bull market?” – June25, 2014

In our previous blog we clearly stated that in our view we are far off from a structural bull market. We anticipated a flattish market for the year and our bet was on defensive sectors outperforming cyclical ones.

In the last 14 months we have seen a flattish market with just 10% rise in Sensex. After the Modi euphoria in May – 2014, majority of investors chased high beta trade and invested heavily in public sector enterprise, construction, oil & gas and real estate. Investors who had taken aggressive bets in these sectors have been hugely disappointed. As we speak there is heightened confusion and general cluelessness on the direction of the market.

Our advice to investors in earlier blog to be aggressive on debt by buying higher maturity funds and being defensive on equities by buying high quality companies has paid off. Our high quality companies’ portfolio has delivered return in excess of 40%. It was a rewarding year for long bond and g-sec investors as well with returns in excess of 12% with a very low level of volatility. The irony is that g-sec funds have outperformed aggressive equity funds having large cyclical bets by more than 5% in last one year.

In our opinion market needs low inflation (not falling inflation), low interest rate (not falling interest rate), high liquidity and low confidence to start a structural bull market. In the current context we have low inflation, comfortable liquidity for capital market and low confidence. We have yet not seen low interest rate but we are extremely confident that we will get there sooner than anticipated. Contrary to last year we have three out of four ingredients to spark a vibrant bull market.

Equities – After making a new high around 29500 on Sensex market has beautifully consolidated around 28000 in the last one year. The market is hunting for cues to breakout above 30000. Majority of participants have apprehension in their minds about index level and valuations. We would like to give our opinion on few major apprehensions:

1.       PE has expanded and no further room for PE to expand – currently we are at historic lows in terms of margins in the case of most domestic facing companies. High interest rates, commodity prices, sharp rupee depreciation and slow reforms had made a big dent on operating margins of the companies. In our opinion we may see big improvement in earnings due to reversal of all the above mentioned factors. In this phase stock prices may move up even after PE contraction and may surprise the street. At the same time we are already seeing few sectors like MNC pharmaceuticals, chemicals, and textiles where PE is expanding with improving fundamentals.

2.     Earning will take time to improve – In June 2015 quarterly results we have seen some improvement in earnings. Contrary to market belief we are of the opinion that small & mid segment will show higher trajectory of growth. Fall in commodity prices & interest rate will have greater impact on that segment of the market. We have already started witnessing earnings growth due to margin improvement. In our opinion companies will use this saving in cost to spur demand. This may lead to faster acceleration in topline growth. CV sales and passenger car sales numbers are already surprising the street.

3.     Interest rate may not go down sharply due to fear of hike in rates by US FED  – In our opinion we are running highest positive real interest rate. We regularly track average of WPI (-4%) and CPI (+4%). As per latest numbers the average was around 0% which makes real interest rate at historic high of 7.55 to 8.0%. This is clearly not sustainable and will fall drastically. In our opinion RBI may be slow in bringing down the rates but markets may price that more aggressively in debt markets. This makes us extremely bullish on long maturity. With respect to US FED rate we believe that in spite of hike we may see rates falling in India and spread between 10 year in US and India may start compressing from current historic high of 5%. We have seen it compressing to as low as 0.50% in the past.

To summarize we believe that the equity market is creating a structural base and is positioning itself for a big move. All the ingredients of a structural bull market are falling in place. Mid and smaller companies have brighter chance of outperforming large cap stocks. Interest rate may fall much faster and much sharper than people on street estimate. We remain extremely positive on long duration funds.

As things stand today majority of investors are still in bank FD’s, accrual funds and liquid funds. We would like investors to show some aggression and divide their money in three parts and invest one part in core blue-chip companies, second part in mid & small caps which can benefit due to faster earning growth and last part in long duration debt funds which will benefit due to fall in interest rate.

Wednesday, 25 June 2014

Are we in a structural bull market?

Reference : “Market at New high… What Next?” – October 30, 2013

In our earlier blog we clearly mentioned that there is huge upside to the market. We also believed that at every higher level consensus in the market will emerge. As we speak we all have started believing that “Ache Din Aane Wale Hain!!!”. That cheerful sentiment can be felt in the market as well.

In the middle of the gloom and doom in August 2013, we all debated endlessly about the political future of India. Market was hesitant too in taking decisive position before elections. We all debated whether once again we may end up with a fractured mandate at the centre. 

On February 14, 2014 things started turning around. Market started moving up in anticipation of a strong mandate. Out of favour stocks and sectors started outperforming broader markets. In just a few months the Sensex moved from 20000 to 24000 before election results. May 16, 2014 onwards which was election result day clearly took the market into a different orbit.

It’s common sense that someone investing today cannot benefit from yesterday’s move. Lot of good things have already got factored into the price by then. The market cap of India is already up from 60 Lac crores to 90 Lac crores which is a 50% growth in investor wealth in a matter of months. This explosive move in the market was because of very high level of underinvestment and lot of pessimism.

A strong consensus is building that we will start seeing improvement in growth rate and fundamentals. This, the experts say, will help us get high valuations and profits for corporates. In short consensus on the street is that we are in a structural bull market but we have a very different take on the subject.

In our opinion a few basic things are required to start a structural bull market – low inflation, low interest rate, high liquidity and low confidence. We are far off from low inflation and low interest rates. Currently we are seeing some level of comfortable liquidity because of strong dollar flows. Confidence has gone up but was at rock bottom a few months back which created a backdrop for strong rise in equities.

If this is not a structural bull market then what next? How will asset classes fare in this new environment?

Equities – In our opinion lot of good news is in the price. We have seen people aggressively allocating money to equities which indicates that risk perception is reducing amongst people at large. Retail participation in daily volume on both the exchanges have gone up and we are also expecting large supply of equities hitting the market and taking advantage of this bullish sentiment.  In this new reality we can only see flattish market or gradual upward or downward move in the immediate term. Market will wait for inflation and interest rates to fall to create a strong structural base. In short we believe we may face an extremely stock specific market with broader indices trading in a tight range.

The risk to this thesis is that world liquidity can get into Indian markets and create an equity market bubble.


Debt – In our opinion a lot of bad news is in price. People at large are worried about the inflation scenario. Participants are exiting long term debt funds and today it is the most hated asset class. As per our observation all inflation levers are cooling off. People are highly invested at the short end of maturity while long duration market is extremely light. This is the perfect scenario for investors to get a huge upside.

The risk to this thesis is that if global liquidity gets into the Indian market it’ll create an inflationary environment as the RBI will strongly intervene to keep currency at 60.

To summarize most of us are extremely conservative on debt side by owning short end of maturity and extremely aggressive on equities by investing in high beta trade. We would urge investors to just flip the trade.


Wednesday, 30 October 2013

Market at New High… What Next?

Reference : “Market Preparing Itself To Scale New High” - December 10, 2012

From December 2012 till date market has made multiple attempts to make new high in the midst of very negative news flows. As we speak we have crossed 21000 on Sensex after a lot of toil, frustration and disbelief.

There were two big black swan events in the market which spooked sentiment on the street. First was the sharp depreciation in rupee and second the reversal of interest rate cycle. In Budget Blog we clearly mentioned about risk on both fronts. After both these events we started believing that the worst is in the price and market will move upward. We are extremely happy with our investors behavior who believed in us and stayed the course against common wisdom.

Now the big question in all our minds is what next? We would like to share our perspective on the market…

1.       Valuations – in our opinion market is extremely cheap. Earnings have not grown in the last 5 years due to currency fluctuation, commodity price fluctuation and government policy interventions. Most of the companies have been resilient in this market and mindfully allocating capital. In every fall weak companies tend to lose competitive advantage and business shifts to stronger players. This will help some of the stronger companies to take advantage of up cycle where earnings tend to grow faster than economic growth because of better utilization of capacity.  Foreign investors have clearly recognised this opportunity and invested heavily in the market at the cost of domestic investors who have largely stayed out.

2.       Sentiment – on this front we have hit rock bottom. Majority of domestic investors are in denial about the recent rise and are highly underinvested in equities. In the last 5 years of savings in India a major bulk has gone to real assets like gold and real estate with the allocation to equities having been reduced dramatically. In any asset class when it is hated the most, it ends up giving a big move. In our opinion equities at new high will make people at large look at it and create more consensus towards it.  

3.       Technical – smart investors have made big investments in the market. With all the bad news we have witnessed huge selling across the board which is getting absorbed by such investors. Once selling becomes light, market will find it easy to move upwards. Market has consolidated beautifully over the last 6 years. On every incremental good news market will start making higher top and higher bottom. Also conviction amongst people will increase and participation will increase.

4.       Long term story – in the bull market of 2003-2007, we all believed that equity is the best asset class to beat inflation and in the long term equities tend to outperform all  asset classes. This theory still remains valid but the general belief in it has vanished. From 1978 to 2013 markets have multiplied 210 times inspite of multiple elections, wars, natural calamities, bad governance, etc. The next 30 years will definitely be better than the last 30 because of the rising aspirations of every Indian. There is no better way to play this story other than equities.

We would request all of you to look at your allocation and correct your underweight position on equities.


Finally I would like share this video with you… Did you know - 

Tuesday, 23 July 2013

Debt Crisis

In continuations to our earlier blog – “Converting Structural problem into cyclical problem” (March – 2013)

As we speak MF Industry is under tremendous pressure with its position in debt market. We have built our largest book of more than 1 Lac crores in long bonds. Our exposure to corporate debt is highest in recent past. Markets have become illiquid with yield spikes. Yield curve has shifted upward by more than 100 BPS on long duration and more than 200 BPS on short duration. Yield curve is once again inverting. Ominous signs for economy. We are staring at sharp decline in economic activity.

It was a black swan event triggered by RBI move to make money expensive in this country. We have been running real interest rate negative for last 3 years. This has built huge speculative activity. People are leveraging and buying house, Gold and spending as value of money is sharply declining. At the same time people at large are speculating in currency, commodities and Bonds. After a long time Reserve Bank has come forward and made real interest rate positive.

Effect of Positive real interest rate


  •  Cost of money will go up
  •  Will provide incentive to saver and hence capital formation in this country
  •  Speculative activities will come down
  • It will also channelize money in more productive investments. It may have big impact on residential real estate. Demand may come off sharply.

Our Recommendations


  • Investors will have to digest extreme volatility in the market
  • Stay away from funds investing in private corporates specially in shorter durations (Accrual Product). Sharp decline in economic activity will increase demand for money by corporates to manage working capital cycle.

We would advise clients to create buckets for different time frame investments and invest in very high quality assets.

Time Frame
Product

Less than one year

Arbitrage Funds / Liquid & Liquid Plus

One Year to 2.5 Years

Bank Debt Funds. Industry at large is expected to launch Bank CD FMP this will create huge demand for Bank CD’s. We would advise clients to build position in advance. Money is expected to move out of short term and duration products. Which will reduce demand for corporate paper at the same time working capital will ensure supply of corporate papers.

More than 2.5 Years

Long term Gilt Funds. This is most liquid part of the market. Idle for FII’s to move in and move out. Crisis in debt market will ensure that more and more people will move towards Bank FD’s. Due to scare of NPA’s banks will find more comfortable to invest in G-Sec. Yield curve is inverted and may remain for some time.


Warning

1.      Avoid Short term funds
2.      Be cautious of underlying securities in debt funds
3.      Avoid Accrual products
4.      Match your investment horizon with very safe and liquid asset class
5.      Smart investors always tend to prefer higher quality asset


We would urge investors to show lot of calm and open mind to new ideas.

Tuesday, 5 March 2013

Budget 2013


Converting Structural problem into cyclical Problem

In the last 3 years we have seen a tight monetary policy and loose fiscal policy. In the last 3-4 months of fiscal 2012-13 we have seen that the government has tightened its belt on fiscal side by curtailing expenditure and reducing subsidies. In Budget 2013 the government is trying to move in the same direction. This will result in a very tight fiscal policy if they are able to achieve 4.80% fiscal deficit. We would like to put our thoughts on various key concerns for the economy –

1.      Inflation –

As per RBI & IMF estimate, WPI for March 2014 is targeted at 7.0% to 7.20%. We would like to go with that estimate as we think reducing subsidy in oil will increase inflation. Also high current account deficit will put pressure on rupee and eventually keep inflation slightly elevated in the 7.0% range.

2.      Interest Rates –

In our opinion we don’t expect a sharp fall in borrowing cost for fiscal 2013 -14 as RBI will be more worried about current account deficit and currency. We expect a cut of around 50 BPS to 75 BPS for the fiscal. Also RBI will find it difficult to transmit cut in interest rate into the real economy.

3.      GDP Growth –

As per CSO estimate and budget estimate GDP is expected to be at 6.10% to 6.70%. Our house view is that in a period of fiscal consolidation it is challenging to spur growth. In our opinion we may undershoot growth numbers for the fiscal.

4.      CAD –

Current Account Deficit (CAD) is at a historical high and may remain at an elevated level due to a very high import bill. Gold imports may come down due to lackluster price movement and fall in investment demand of gold. High CAD will keep currency vulnerable and volatile.

5.      Fiscal Deficit –

The government is focusing on controlling fiscal deficit at 4.80% of GDP level. There are certain moving parts in this budget. For example spectrum auction and disinvestment together are expected to garner almost 90000 Crores. This may be difficult to achieve. Also revenue growth of around 18% may be difficult if growth decelerates. But there is certain flexibility in planned expenditure which can be curtailed to achieve a 4.80% fiscal deficit.


Asset Market View

1.      Equity Market –

In a period of reasonably high inflation and low growth – high quality stocks that can protect margin will outperform. We would advise clients to stick to high quality stocks in this period. In the next 2-3 quarters we expect cyclical slowdown and deep cyclical stocks may disappoint investors. This will make strong bottom for these stocks. We would advise our clients to finally look at these stocks in the next 2-3 quarters and start loading them up in their portfolios.

2.      Debt Market –

Currently we have an inverted yield curve. Short term rates are in the range of 9% plus and long term rates are at 8%. In our opinion yield curve will start flattening out after April. We would advise our clients to split their debt book between short term and long term bond funds.

(Imp – In the entire hypothesis commodity prices including OIL can act as beta. Any fall in OIL & commodity prices can change the whole equation)